
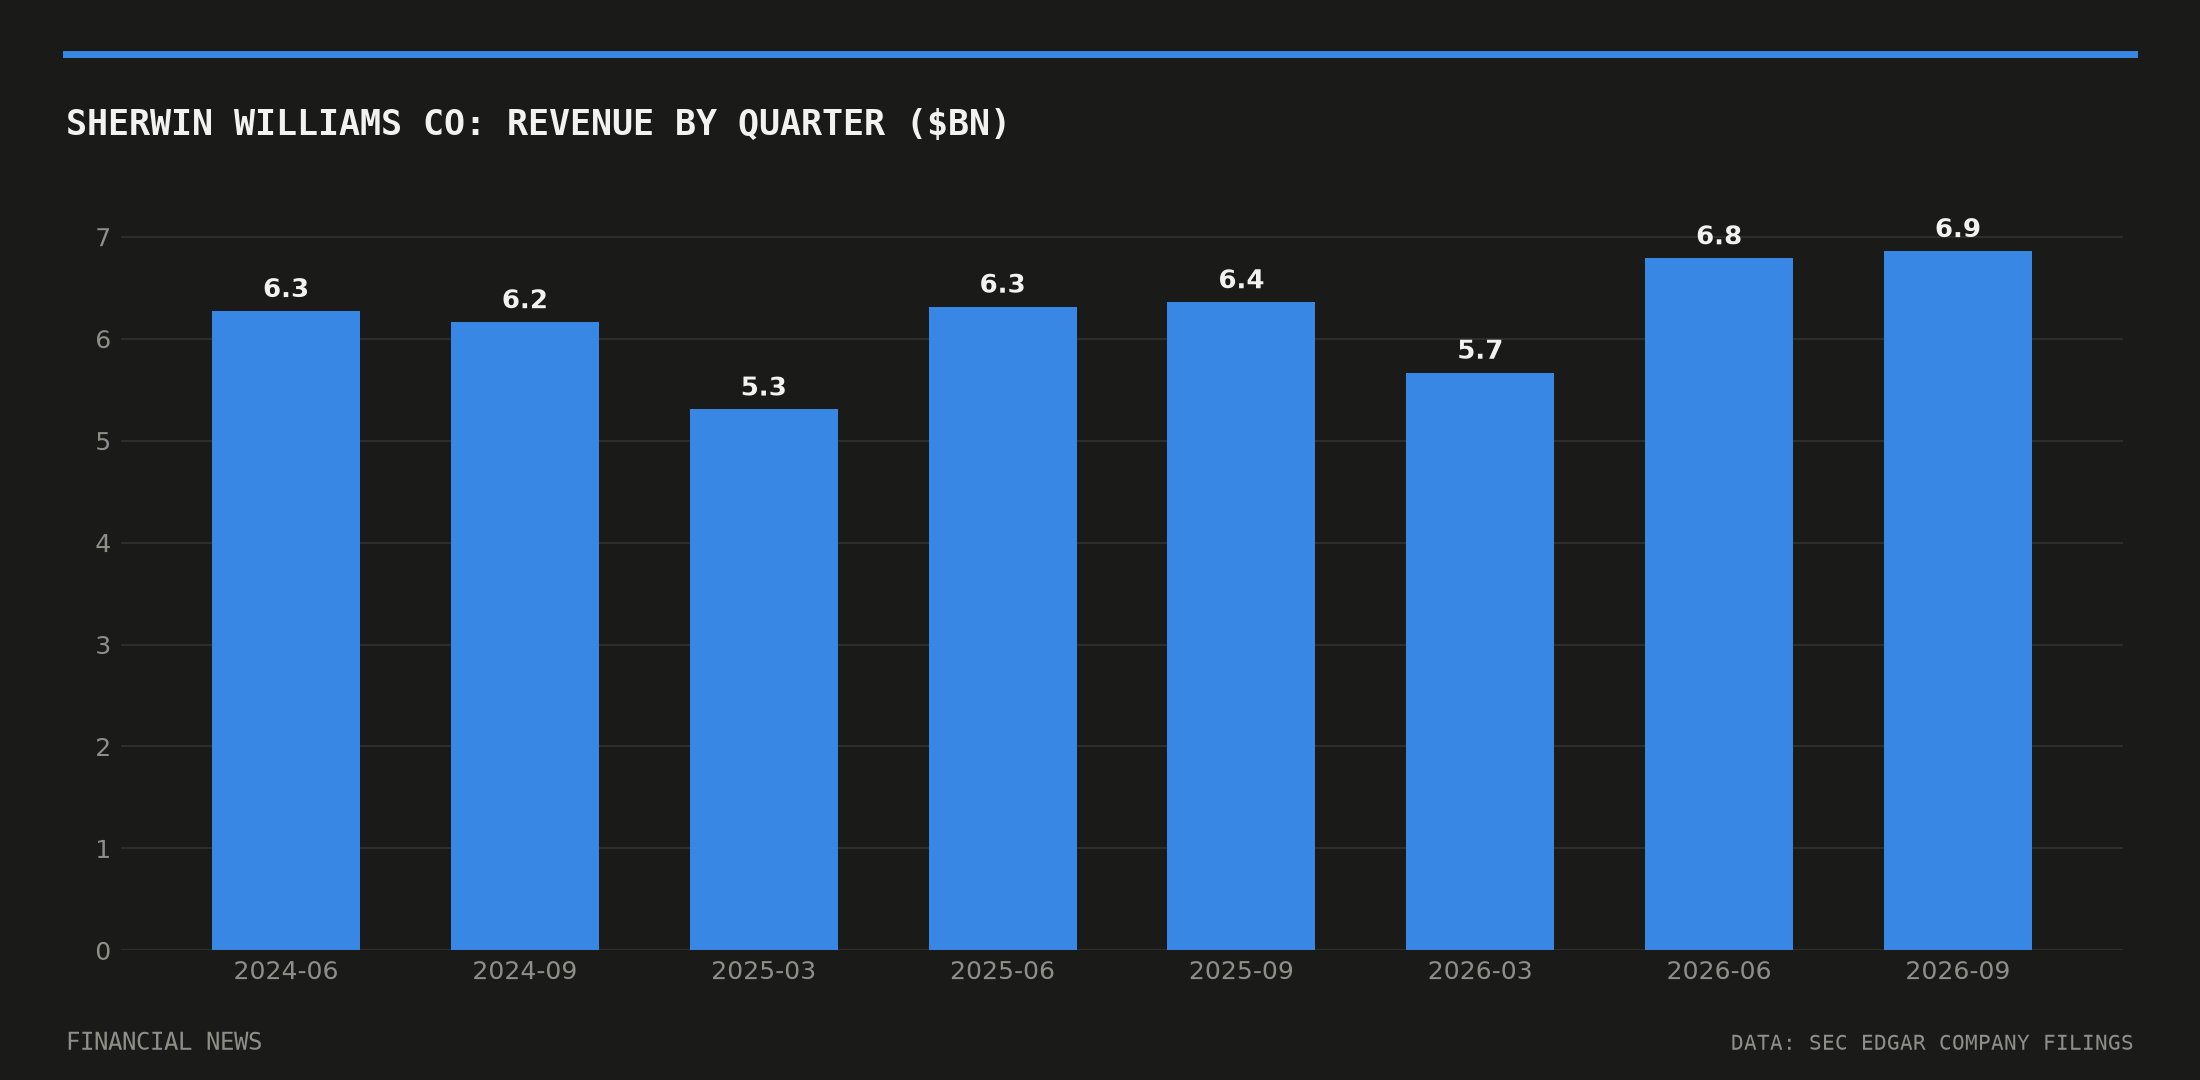
The Sherwin-Williams Company (NYSE: SHW) reported third-quarter 2026 results on 27 October, posting net sales of $6.86bn for the period ended 30 September.
That marks growth of 7.9% from $6.36bn a year earlier, according to the company’s 10-Q filing with the US Securities and Exchange Commission. Net income, however, fell 1.5% to $821.0m from $833.1m in the same quarter last year.
Sherwin-Williams Q3 2026 earnings: sales up, profit down
Diluted earnings per share came in at $3.38, up 0.9% from $3.35 a year earlier, even as net income declined, a gap the paint and coatings group attributes to a lower share count after buybacks. Adjusted diluted EPS, which strips out one-off items, rose 1.1% to $3.63 from $3.59.
That adjusted figure missed Wall Street’s consensus estimate of roughly $3.69, a shortfall of about 1.6%, as first reported by Investing.com. Shares fell 1.28% to $330.87 in premarket trading after closing at $335.16 the previous session, Investing.com said.
Chief executive Heidi Petz said the quarter’s top-line performance reflected the strength of the group’s strategy. ‘Our third quarter sales performance reflects the strength of our strategy and the value customers are placing on our products and services,’ she told analysts on the earnings call.
Buybacks do the heavy lifting
The arithmetic behind the quarter is unusual: sales climbed nearly 8% and GAAP EPS still rose, yet net income fell. The explanation lies largely in capital returns rather than operating performance. Sherwin-Williams returned $749m to shareholders in the third quarter through buybacks and dividends, taking the year-to-date total to roughly $3.0bn, according to Investing.com.
Management conceded on the call that sales-to-earnings conversion fell short of its own standard in the quarter, pointing to raw material costs, supply chain pressure and dilution from recent acquisitions, as The Motley Fool’s transcript of the call shows. The Consumer Brands Group, which includes the Suvinil business acquired in Brazil, saw sales rise 21.7%, but much of that gain came from the acquisition itself and favourable currency moves rather than underlying volume, a dynamic management cited as a factor behind margin pressure.
EBITDA rose 3.4% to $1.39bn, with adjusted EBITDA up 3.3% to $1.40bn, a margin of 20.5%. Operating cash flow in the quarter fell 15.5% to $1.10bn, though the year-to-date figure is up 10% at $2.6bn, Investing.com reported.
Guidance narrowed, housing backdrop still soft
Sherwin-Williams narrowed its full-year 2026 guidance alongside the results. The company now expects GAAP diluted EPS of $10.92 to $11.22 and adjusted diluted EPS of $11.85 to $12.15, according to the group’s earnings release filed with the SEC.
The update comes against a housing market that remains a headwind for the sector. Single-family housing completions fell by a high-single-digit percentage in the quarter even as new residential paint demand grew, a divergence management flagged on the call. The backdrop includes a US unemployment rate that ticked up to 4.2% in September from 4.1% the prior month, according to Federal Reserve data, a labour market signal that bears on renovation and new-build demand alike.
Trading activity around the release was elevated. FINRA’s daily short-sale data show the short-volume ratio for Sherwin-Williams shares jumped to 0.437 on earnings day, up from a range of 0.298 to 0.31 earlier in the week, according to FINRA figures.
For a company that has built its reputation on steady, repeatable margin discipline, the quarter’s message was mixed: a strong top line, a GAAP profit print flattered by the buyback programme, and management’s own admission that conversion of sales into earnings has slipped from standard. The narrowed guidance range gives investors a tighter window to judge whether the fourth quarter closes that gap.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.