
Hilton Worldwide Holdings (NYSE: HLT) reported third-quarter 2026 results on 27 October, posting net income of $536m against $421m a year earlier. Diluted earnings per share came to $2.37, up from $1.78 in the same period last year, according to the company’s earnings release.
System-wide comparable RevPAR rose 5.8% on a currency-neutral basis, Hilton said, as reported by Hotel Business. Adjusted EBITDA reached $1,058m for the quarter.
Hilton Q3 2026 results beat prior quarters
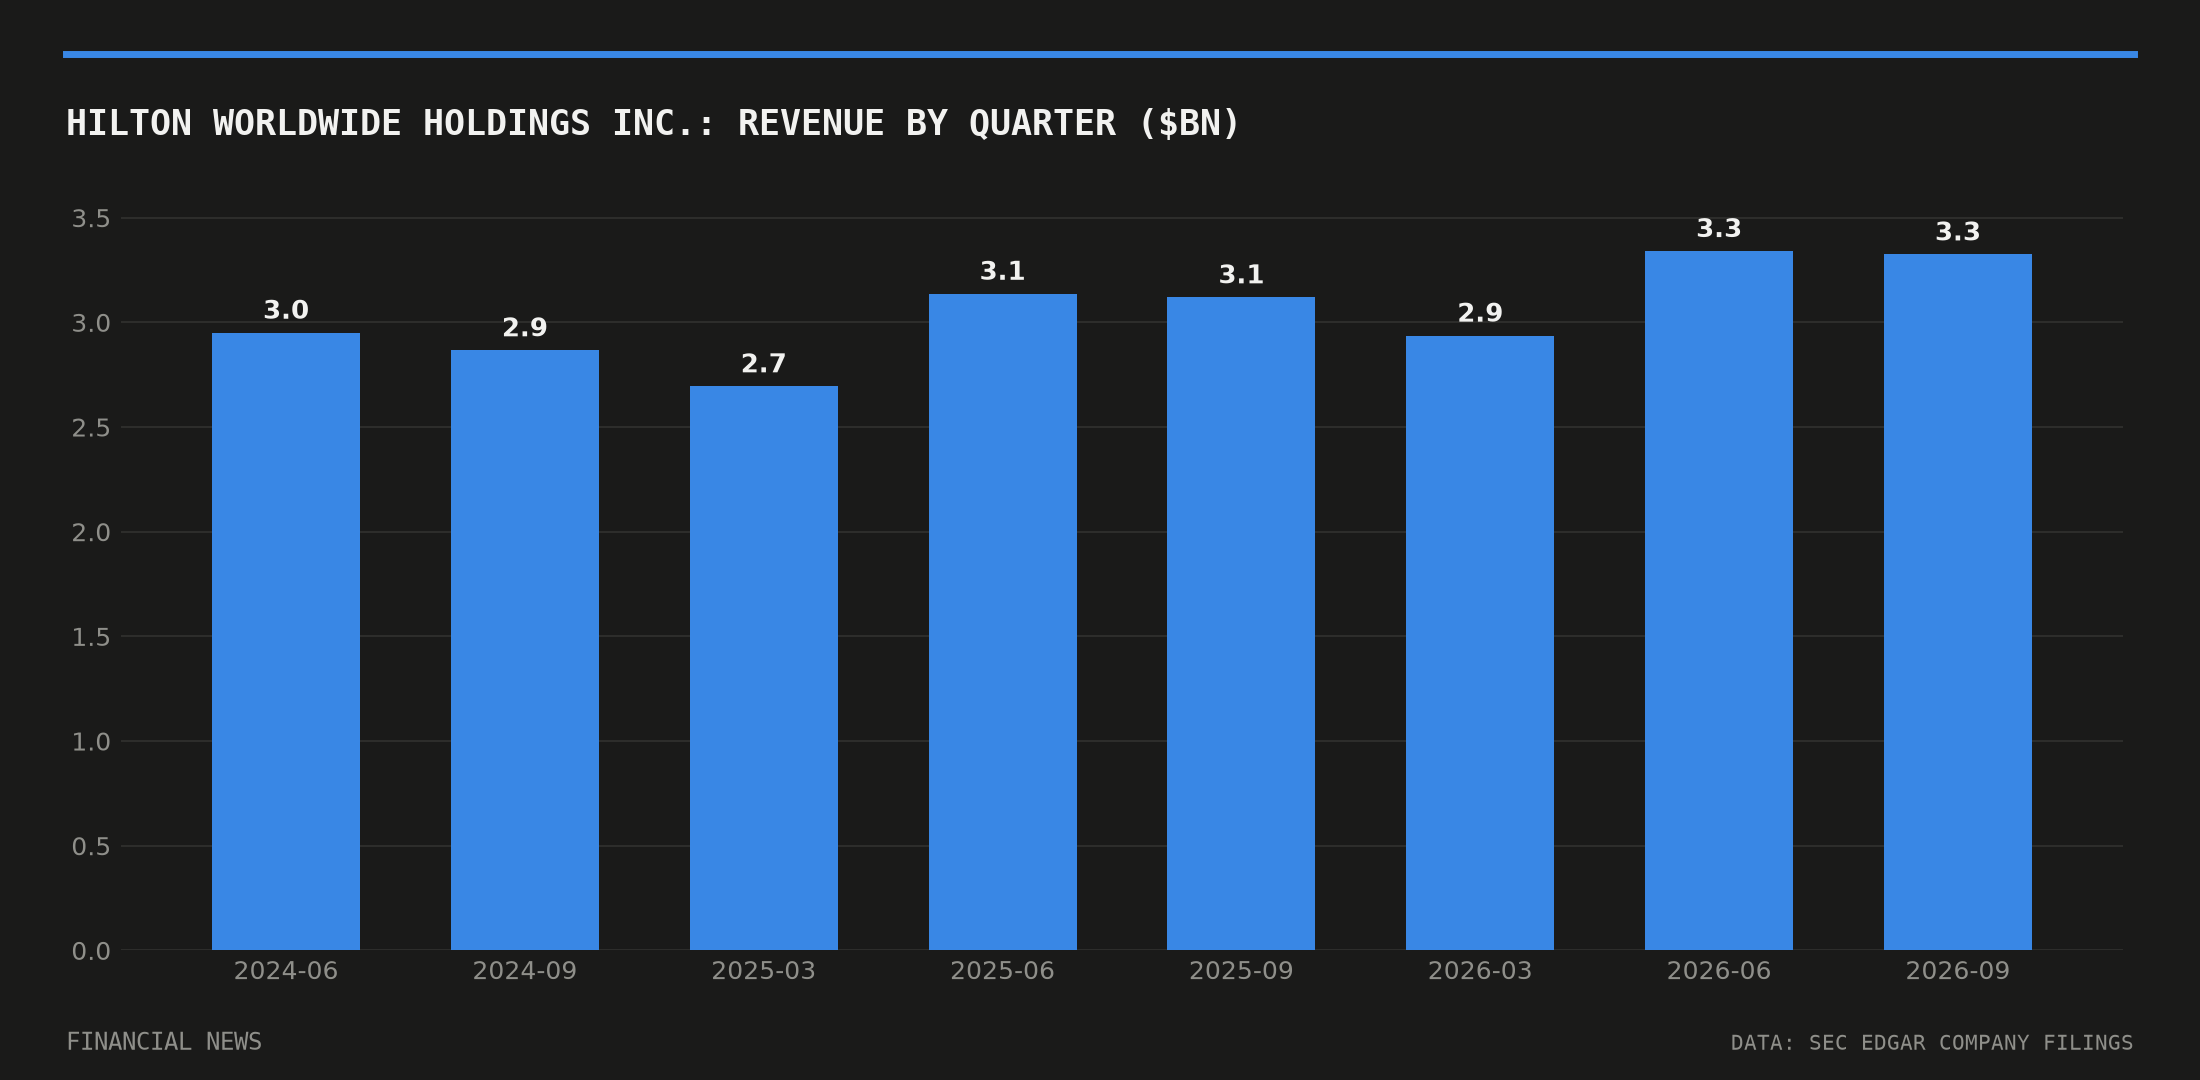
Adjusted diluted EPS, which strips out special items, was $2.45. The figures are drawn from Hilton’s quarterly filing with the SEC, which also shows revenue of $3,325m for the three months to 30 September, up from $3,120m in the prior-year quarter.
The quarter extends a run of sequential improvement. Net income climbed from $385m in the first quarter of 2026 to $482m in the second quarter, before reaching $536m in the third, according to the company’s 10-Q filings across the year. Diluted EPS has followed a similar trajectory, rising from $1.66 in the first quarter to $2.10 in the second and $2.37 in the third.
RevPAR gain carries a tailwind
Management pointed to a mix of World Cup-related demand and favourable calendar shifts behind the strength, with US RevPAR up 7.0% on robust business transient demand, according to a transcript of the earnings call. Net unit growth ran at 6.0% year-on-year, with roughly 27,000 gross room additions marking what the company described as its largest organic opening quarter on record.
Hilton’s guidance for the full year calls for system-wide RevPAR growth of 4.0% to 4.5%, net income of $1,909m to $1,923m, and Adjusted EBITDA of $4,060m to $4,080m, per the earnings release filed with the SEC. That range implies a more modest pace of RevPAR growth in the fourth quarter than the 5.8% posted in the third, raising the question of how much of the quarter’s gain reflected one-off demand rather than a durable trend.
Shares trade near recent highs
Shares closed at $344.80, up 0.9% on the day and 7.4% over the prior 20 trading sessions, with volume running 1.6 times the 20-day average, according to consolidated US exchange data. The stock has traded in a range of $320.46 to $363.84 over the past month.
FINRA short-sale data show HLT’s daily short volume ratio climbing from 0.306 on 23 October to 0.552 on 27 October, the day of the release, pointing to heavier short-side trading activity around the print, according to FINRA’s daily short sale volume data.
The results land against a tighter macro backdrop than a year earlier. The 10-year US Treasury yield stood at 5.0% on 26 October, with the unemployment rate at 4.2% in September, according to Federal Reserve data. Higher borrowing costs and a softer labour market have weighed on consumer discretionary spending more broadly, a factor hotel operators watch closely when assessing the durability of leisure and business travel demand.
Management and franchise fees, a closely watched line for asset-light hotel operators, grew 9.5% year-on-year, contributing to the 8.4% rise in Adjusted EBITDA, according to coverage of the earnings call. That growth rate in fee income has outpaced RevPAR gains for several quarters running, reflecting continued expansion of Hilton’s room count even as same-store revenue growth moderates.
Investors will next look to fourth-quarter trading updates to gauge whether the World Cup and calendar effects that boosted the third quarter fade as guided, or whether underlying demand proves sturdier than the company’s own outlook suggests.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.